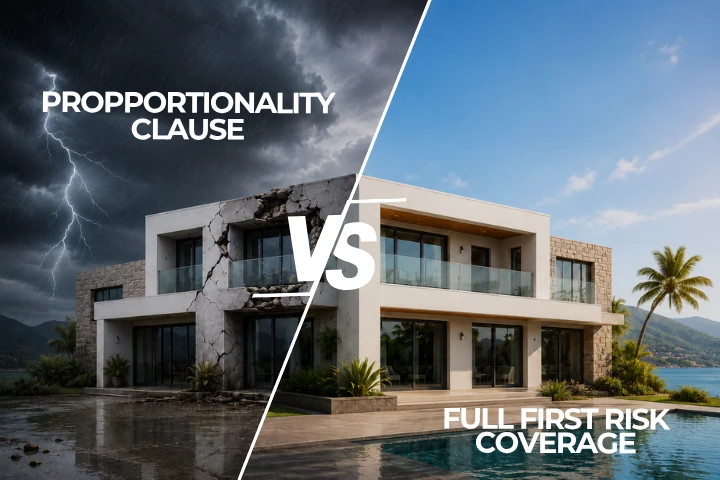
When Expats purchase home insurance in Mexico, they often assume coverage works the same way it does back home. Unfortunately, this assumption can lead to serious financial exposure, especially when a policy includes a Proportional Indemnity clause instead of Full First Risk Coverage.
Understanding the difference between these two concepts can be the difference between a smooth claim… and a painful out-of-pocket expense.
Let’s break it down in simple terms.
WHAT IS PROPORTIONAL INDEMNITY?
Proportional Indemnity means that the insurance company will only pay a proportion of the loss if the property is underinsured.
In other words:
If your home is insured for less than its real replacement value, the insurance company assumes you chose to self-insure part of the risk, and they will reduce the claim payment accordingly.
Example:
• Real replacement value of the property: USD 500,000
• Insured value on the policy: USD 300,000
• You insured only 60% of the real replacement value
• Claim damage: USD 100,000
The insurer may only pay 60% of the loss:
• Insurance pays: USD 60,000
• You pay out of pocket: USD 40,000
This applies even if the loss is partial, not just in total losses. And don’t forget the corresponding applicable deductibles or coinsurance (which vary depending on the claim).
WHY PROPORTIONAL INDEMNITY IS SO COMMON IN MEXICO
Many expats unknowingly fall into this situation because:
• They chose that scheme either for price, because that insurance carrier only offers that option, or the broker didn’t address that when providing the quotes
• They want to lower the premium of the policy
• They assume partial damage equals full payment
• They are not properly advised on how homes are valued in Mexico
This is one of the most common and expensive mistakes we see.
WHAT IS FULL FIRST RISK COVERAGE?
Full First Risk Coverage works differently.
With this structure, the insurer agrees to pay losses up to the insured amount without applying proportional penalties, as long as the loss does not exceed the policy limit or the property isn’t overinsured.
Example:
- Real replacement value: USD 500,000
- Insured amount: USD 300,000
- Claim damage: USD 100,000
With Full First Risk Coverage:
• The insurer pays the full USD 100,000 (less the corresponding deductibles and/or coinsurance)
• No proportional reduction applies
WHY THIS CLAUSE MATTERS SO MUCH FOR EXPATS
For foreign homeowners in Mexico, replacement costs can be surprising:
• Labor pricing differs from market value
• Materials may need to be imported
• Coastal and seismic zones have higher rebuild standards and costs
• Inflation and currency changes affect real costs
Without proper guidance, many policies look cheaper upfront but become extremely expensive at claim time.
WHICH OPTION IS BETTER?
There is no universal answer, but there is a correct strategy.
• Proportional Indemnity may work only if the home is insured at 100% of its true replacement value
• Full First Risk Coverage offers more flexibility and protection when:
– Valuation is complex or uncertain
– You feel comfortable insuring your property up to a certain amount that is not its 100%
– It’s a matter of budget
The key is proper assessment, not assumptions.
THE BOTTOM LINE
Home insurance in Mexico is not just about buying a policy; it’s about structuring it correctly.
Two policies with the same price can behave very differently during a claim. And once a loss occurs, it’s too late to make the changes for that one claim.
That’s why working with a broker who understands how policies are written and how claims are adjusted in Mexico is essential.
CONCLUSION:
Before you purchase — or renew — your home insurance in Mexico, let a specialist review your coverage structure.
A short review today can save you tens of thousands of dollars tomorrow.
Contact us to receive a customized quote designed specifically for expats in Mexico
Get clarity. Get proper protection. Get insured the right way.