Holiday travel insurance helps protect travelers against eligible medical emergencies and unexpected disruptions before or during a trip. Depending on the policy, benefits may include emergency hospitalization, medical transportation, trip cancellation, delayed flights, lost baggage, medically necessary hotel accommodations, and 24/7 assistance. Not every unexpected event is covered, and benefits, exclusions, and limits vary widely. Travelers visiting Mexico or heading abroad during the busy holiday season should review their existing medical and credit card coverage before choosing a policy.
Key Takeaways
- Private medical treatment in Mexico can be costly, especially when surgery, hospitalization, or intensive care is necessary.
- Travel insurance may cover qualifying trip cancellations, delayed flights, baggage issues, and other assistance needs—not just medical emergencies.
- Premium credit cards do not necessarily provide comprehensive emergency medical or evacuation coverage.
- Medical and trip-related benefit limits vary substantially between policies.
- Purchase early enough to understand eligibility, covered reasons, waiting periods, and the assistance process.
End-of-Year Travel Risks: What Your Insurance Actually Covers During Holiday Trips
Holiday travel is about reconnecting with family, escaping winter weather, and enjoying a well-earned break. Expats living in Mexico may fly back to the United States or Canada, retirees may host visiting relatives, and international travelers may arrive in Mexico for beaches, celebrations, and warm weather. Most people plan flights and hotels carefully. Far fewer check what would happen if an emergency interrupts the itinerary.
A hospitalization, missed connection, missing suitcase, or urgent family matter can transform a holiday into an expensive logistical problem. Holiday travel insurance is meant to reduce certain financial consequences and connect eligible travelers with practical assistance. Understanding its benefits—and its limitations—before departure is essential.
This guide explains why rising medical costs matter, why credit card benefits may leave gaps, what travel insurance can cover beyond medical emergencies, and how to compare protection without paying for benefits you do not need.
Why Holiday Travel Insurance Matters More Than Ever
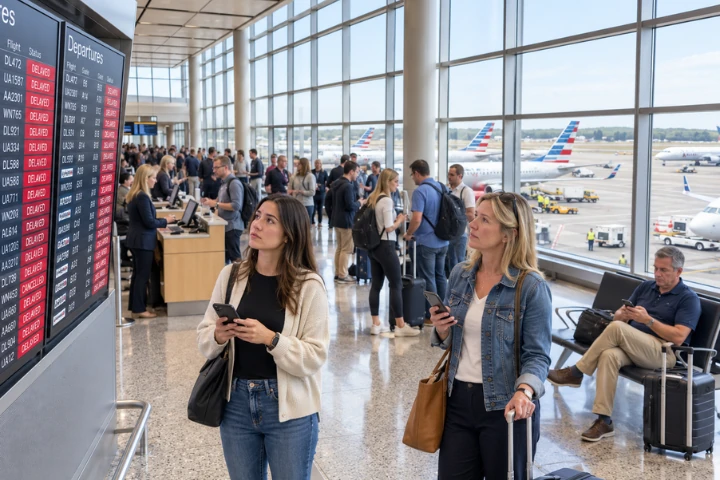
The end of the year often means crowded airports, weather-related disruption in some destinations, expensive prepaid reservations, and schedules with little room for change. A delayed flight may cause a missed connection; a bag that does not arrive can leave a traveler without medication or warm clothing; a medical event can require extended accommodation or rearranged flights.
Travel insurance is a contract that covers specified risks and may provide assistance services during temporary travel. It is not a blanket promise to reimburse every inconvenience. A qualifying event must meet the policy’s conditions, and the appropriate benefit must be included. That distinction is especially important during holiday trips, when travelers often assume that any canceled flight or changed plan will generate a payout.
For Expats, snowbirds, retirees, digital nomads, and travelers in general, the additional logistical support can matter as much as reimbursement. A 24/7 assistance team may help explain procedures, coordinate eligible medical services, or direct travelers toward the appropriate next steps when they are far from home.
Medical Inflation in Mexico: Why Travelers Should Pay Attention
Mexico is often viewed as a less expensive healthcare destination than the United States. And that is true. However, less expensive does not mean “cheap”. Serious treatment in a private hospital can still result in a large bill. Surgery, imaging, specialist fees, hospitalization, medication, and intensive care can accumulate rapidly, particularly when several services are needed during one admission.
Mexico has become one of the most expensive countries worldwide for private healthcare.
Mexico has also experienced significant medical cost pressure. Aon’s 2026 medical trend outlook, as reported by El Economista, projected a 14.8% increase in private medical costs in Mexico for 2026. This is a medical cost trend estimate, not an assertion that every hospital bill rises by exactly 14.8%, and it should not be confused with general consumer-price inflation. Different industry surveys use different methodologies and should not be treated as a definitive country ranking.
The impact of sustained increases becomes clearer over time. As a purely mathematical illustration, a service costing $10,000 would cost about $15,130 after three consecutive annual increases of 14.8%. That illustration is not a quotation for a real procedure or a prediction of future hospital prices. It simply shows why assuming that medical care costs what it did a few years ago can be risky.
Consider a visitor who has an accident and needs emergency surgery, several days of inpatient care, tests, and follow-up treatment. The final bill could reach tens -or even hundreds- of thousands of dollars, depending on the condition and hospital. Travelers should not rely on anecdotes or a destination’s reputation for affordability when assessing the level of emergency medical protection they may need.
Can Your Credit Card Replace Travel Insurance?
A premium credit card can provide useful travel-related benefits, but card ownership does not guarantee comprehensive medical insurance abroad. Coverage can depend on the issuing bank, card tier, the specific trip payment method, eligible travelers, covered reasons, and claim deadlines. Some cards offer baggage or trip-delay protection but limited—or no—emergency medical or evacuation benefits.
The U.S. Centers for Disease Control and Prevention advises travelers to consider travel medical and medical evacuation protection and to verify what existing policies actually cover. A high available credit limit is not itself an insurance benefit. If a hospital bills your card, you normally remain responsible for the charge unless a valid insurance benefit pays or reimburses it.
| Question to verify | Credit card benefits | Didicated travel plan |
|---|---|---|
| Emergency hospital care | May be absent or restricted | Available in medical-focused plans |
| Medical transportation | Not guaranteed | May be included with conditions |
| Trip cancellation | Often specified covered reasons | Depends on insured reasons and limits |
| Baggage and delays | Varies by card | Varies by selected plan |
Before you leave, ask the card issuer for the current guide to benefits. Check medical limits, medical evacuation, destinations, who qualifies as an insured traveler, and whether you must pay for travel using that card. If these answers are unclear, do not assume that your holiday trip is protected.
What Does Holiday Travel Insurance Actually Cover?
1. Emergency Medical Treatment and Hospitalization
Medical assistance is often the central benefit of a travel policy. Depending on the product, eligible unexpected accidents or illnesses may qualify for emergency consultations, hospital stays, diagnostic tests, medically necessary surgery, and prescribed medication. The amount available is capped by the policy’s applicable medical limit, and some services have separate sublimits.
For example, a traveler experiencing acute abdominal pain that requires emergency surgery may be able to use the plan’s medical assistance benefit, provided the event is covered. Certain assistance providers may coordinate direct payment with eligible hospitals after authorization, but this is not guaranteed everywhere. Outpatient services or smaller claims may need to be paid first and submitted for reimbursement.
2. Medical Transportation and Repatriation
A nearby hospital may be unable to provide a required level of care. Some travel policies include medically necessary transportation to an appropriate facility or repatriation assistance. This is generally a coordinated medical transfer, not a benefit allowing travelers to select any hospital or destination they prefer.
The CDC notes that medical evacuation can be extremely expensive, with costs varying considerably according to distance, medical needs, and destination. Review whether transportation is included, whether any separate limit applies, who must authorize it, and which circumstances qualify.
3. Trip Cancellation and Interruption
Holiday itineraries often include nonrefundable plane tickets, hotel deposits, cruises, and activities. Trip cancellation coverage may reimburse eligible prepaid losses when a specifically covered event prevents departure. Trip interruption benefits, if included, may address qualifying events after travel begins. These are distinct benefits: never assume one is included merely because the other appears in a summary.
A sudden qualifying illness or the death of an eligible family member may be a covered reason, subject to the policy or plan. Changing your mind, having a scheduling conflict, or canceling because of ordinary concerns may not qualify. Always compare the cancellation limit with your actual nonrefundable commitments and read the covered-reason definitions.
4. Flight Delays and Other Disruptions
A long flight delay can cause missed connections, extra meals, overnight accommodation, or changed transportation arrangements. Some travel plans offer a fixed benefit or reimbursement for eligible delays or cancellations. In Guardian’s sample quotation, the listed benefit for certain delayed or canceled flights requires a minimum six-hour delay; some plans have no such benefit at all.
The event’s cause, duration, eligibility, and required documentation determine whether compensation applies. Do not assume that a six-hour delay triggers every available travel benefit or that airlines and travel insurers pay for the same expenses under the same rules.
5. Baggage Loss, Damage, and Delay
Permanently lost baggage, baggage damage, and delayed delivery are separate problems and may have separate benefits. For example, arriving at a winter destination without checked luggage can create urgent costs for essential clothing. An eligible baggage delay benefit may help with qualifying necessities, while a lost-baggage benefit may address an eligible permanent loss.
Keep the airline’s baggage report, baggage tags, receipts, and written correspondence. Check item sublimits, excluded valuables, proof-of-loss rules, and whether benefits are secondary to reimbursements received from the carrier. A policy that lists “baggage loss” does not necessarily cover every missing personal item.
6. Hotel Convalescence and Unexpected Accommodations
Some plans include hotel convalescence or recovery accommodation benefits when a traveler cannot safely continue or return home after a qualifying medical event. Such benefits often depend on a medical recommendation and assistance-company authorization. They are different from ordinary delay-related hotel expenses, which may require separate coverage.
For example, a traveler discharged from a hospital may be instructed not to fly immediately. If the plan includes the applicable benefit and its requirements are satisfied, eligible hotel costs may be covered up to the stated limit. An optional vacation extension or preferred room upgrade is not the same thing.
7. Family Emergencies and Early Return
Certain plans help arrange or pay for eligible early return travel after a specified serious accident, illness, or death involving a qualifying relative. Some include family-member transportation when an insured traveler is hospitalized under defined circumstances. Terms such as “first-degree family member” have policy-specific meanings; check the relevant definition rather than assuming every relative is included.
8. Additional Assistance Services
Depending on the plan, assistance may include emergency dental care, help after the loss of travel documents, legal assistance, psychological assistance, minor escort services, emergency message transmission, and cruise-related support. Some plans also list services such as AirHelp, SmartDelay, assistance involving amateur sports, or emergency transfer of funds.
These benefits are not interchangeable with cash indemnity or unlimited coverage. A “transfer of funds” service may involve arranging access to your own funds rather than gifting you that amount. Services branded AirHelp or SmartDelay have separate usage conditions. Travelers should confirm the exact scope of every service before relying on it.
How Much Does Holiday Travel Insurance Cost?
One of travel insurance’s greatest advantages is its affordability, especially compared with the financial protection it provides.
The cost of a policy varies depending on factors such as the traveler’s age, destination, trip duration, and selected coverage limits. However, travel insurance is generally a relatively inexpensive way to protect yourself against unexpected expenses.
A Small Investment, Significant Protection
Think about it: depending on your trip and selected plan, you could spend just $50 on travel insurance and potentially have access to $50,000 or more in medical coverage.
This means a relatively small investment could help protect you from tens of thousands of dollars in unexpected medical bills.
And the value goes well beyond medical emergencies. Depending on the plan, your coverage may also include trip cancellations, flight delays, lost luggage, emergency accommodations, medical transportation, and 24/7 assistance.
When compared to what travelers typically spend on flights, hotels, restaurants, and activities, travel insurance can represent just a small fraction of the overall vacation budget.
Focus on Value, Not Just Price
While affordability is important, the cheapest policy isn’t necessarily the best choice. Medical coverage limits, destinations, exclusions, and assistance benefits should always be considered.
The goal isn’t to buy the most expensive policy, nor is it to buy the cheapest one. It’s to make a smart investment that could save you from a major financial setback while traveling.
At Guardian Insurance MX, we help travelers compare options and choose protection that matches their needs, destination, and budget.
Do You Need Travel Insurance if You Already Have Health Insurance?
Not necessarily for the same purpose. Long-term private or international health insurance generally focuses on ongoing medical needs in its insured territory. Travel insurance typically focuses on emergencies and specified disruptions during temporary travel. Some people need both; others already have adequate medical coverage abroad and mainly want trip-related protection.
For example, an expat who has comprehensive private medical coverage within Mexico but no coverage for treatment in the United States should not assume a holiday visit to the U.S. is medically protected. And it’s the same case the other way around.
A carefully selected temporary travel medical product might address that gap if the trip and traveler qualify. Conversely, a person with substantial worldwide medical coverage may wish to evaluate only the baggage, cancellation, and delay benefits.
Check the insured/covered territory, exclusions, maximum trip duration, pre-existing condition provisions, and whether the policy is valid in your country of residence or origin. A policy marketed as worldwide may still contain specific territorial or residency restrictions.
Common Exclusions and Limitations to Review
Pre-Existing Medical Conditions
Some policies exclude pre-existing conditions; others provide narrowly defined benefits for an unforeseen acute episode. Some of our Guardian travel coverage plans list pre-existing-condition dollar amounts, but this does not mean unrestricted coverage for any chronic or previously diagnosed condition. Medical history, stability requirements, definitions, and exclusions matter.
Routine Care and Elective Treatment
Travel insurance is not ordinarily designed to pay for regular checkups, preventive services, ongoing prescriptions, or elective procedures. Read the emergency definition and the medication benefit terms carefully.
Sports, Activities, and Destinations
Through standard travel medical plans, amateur sports benefits may be available, while more hazardous activities can be limited or excluded.
Sports or activities of a higher risk such as skiing, scuba diving, high-altitude activities, competitions, and motorized recreation are usually only available through upgrades or specific plans for those purposes. Likewise, destination eligibility and coverage territory must fit the full itinerary.
Known Events and Timing
Buying insurance after a flight cancellation has been announced or after a medical problem has arisen does not generally make that event eligible. Some products allow purchase after departure, but waiting periods or restrictions may apply. Coverage begins according to the actual policy terms, not whenever the traveler expects it to begin.
How to Choose Coverage Before the Holiday Season
- Start with your itinerary: identify destination countries, stopovers, duration, activities, and where you legally reside.
- Review existing health insurance: check international medical coverage, emergency treatment limits, and evacuation provisions.
- Review credit card benefits: request the current benefit guide and confirm eligibility requirements rather than relying on marketing language.
- Choose medical limits realistically: weigh potential hospitalization costs against the amount you could comfortably pay yourself.
- Match cancellation benefits to prepaid commitments: consider nonrefundable flights, accommodations, and tours.
- Confirm assistance procedures: find out who to call, whether services require authorization, and how direct hospital payment or reimbursement works.
- Check exclusions before paying: especially pre-existing conditions, known events, destination restrictions, and recreational activities.
What to Do When an Emergency Happens Abroad
First, seek urgent care or contact local emergency services if the situation is life-threatening. Do not delay necessary treatment simply to obtain prior insurance authorization. As soon as reasonably possible, contact the emergency assistance number shown on your policy and follow the instructions for coordinating eligible treatment or claims.
Maintain copies of your policy or coverage certificate, passport details, medical notes, prescriptions, hospital invoices, receipts, airline notices, and baggage incident reports. Notify the appropriate provider promptly and record case numbers and the names of people who assisted you. Ask which expenses require preauthorization, which can be billed directly, and what the submission deadlines are.
Good documentation does not guarantee payment for an excluded expense, but it makes legitimate claims easier to evaluate and reduces avoidable delays. When possible, keep digital copies accessible even if your phone, wallet, or suitcase is lost.
Frequently Asked Questions
It can be. Even a brief trip can involve expensive emergency treatment or disruption. Compare the premium with your financial exposure and existing coverage.
Many plans cover qualifying unexpected illnesses and accidents in Mexico, subject to residency, itinerary, geographic rules, medical limits, and exclusions.
Not without checking the guide to benefits. Some cards offer trip protections but little or no emergency medical or medical evacuation coverage.
Some plans cover specified cancellation or delay events, subject to qualifying reasons, duration thresholds, limits, and documentation. Others do not.
A policy with baggage-loss benefits may pay for qualifying losses up to its limits. Notify the airline immediately and retain written reports and receipts.
Sometimes only in narrowly defined circumstances. Some plans exclude them entirely. Verify the specific medical definitions, limitations, and benefits.
Yes, provided the claim meets the criteria for direct payment, which normally means hospitalization for a minimum of 24 hours. Certain assistance providers may coordinate authorized direct payment to an eligible hospital. This is not guaranteed for every service or provider.
Some plans cover qualifying medically necessary convalescence stays or specified travel delays. Routine extensions and upgrades are generally not included.
Yes, some products allow it, sometimes with waiting periods or other restrictions. Known events and earlier losses cannot be insured retroactively.
There is no universal amount. Consider destination medical costs, your existing insurance, activities, age, and what you could afford to pay yourself.
Many assistance-based plans list medical transport, but approved medical necessity, destination eligibility, and contractual conditions determine the service.
No. Travel plans generally address temporary emergencies and specified disruptions; international health policies are designed for broader ongoing medical needs.
Expert Insight
The most useful question is not simply “Do I have insurance?” It is “Would the insurance I have respond where I am traveling and for the event that concerns me?” A traveler can have excellent health coverage in their country, yet have no protection during a holiday trip abroad. Another can have a premium credit card with strong baggage benefits but minimal medical protection. A third can purchase an inexpensive plan whose emergency medical limit is insufficient for a severe hospitalization.
At Guardian Insurance MX, we encourage travelers to compare the real gaps: where care is covered, how much protection is available, whether the travel disruption benefits fit the value of the trip, and what the assistance process looks like. A policy is valuable not only because of its stated limits but also because the traveler knows how to use it. Ask for clear explanations of emergency definitions, direct-payment conditions, exclusions, and claims procedures before departure.
Common Mistakes to Avoid
- Assuming a credit card covers medical emergencies: Card benefits may be narrower than advertised and may require payment of the trip with that card.
- Buying only on price: A low premium can accompany medical or cancellation limits that do not match the risks.
- Confusing travel and regular health insurance: Emergency-focused travel protection does not replace ongoing health coverage.
- Treating cancellation coverage as cancel-for-any-reason: Most standard policies list specific qualifying reasons.
- Waiting until the problem is already known: Insurance generally does not pay retroactively for known or occurring events.
- Ignoring pre-existing medical conditions: An existing diagnosis can trigger exclusions or special limitations.
- Overlooking sports and territorial restrictions: Activities and destinations must fall within the applicable terms.
- Not saving an assistance number or documentation: Delayed notice and missing records can complicate a legitimate claim.
Final Thoughts
Holiday travel insurance can help reduce the financial and logistical impact of eligible surprises, from emergency hospitalization to lost baggage and qualifying flight disruptions. As private healthcare costs rise, travelers should not assume that treatment abroad will be inexpensive, or that a premium credit card automatically provides adequate medical protection.
Before leaving, review your existing medical benefits, confirm the true scope of credit card protection, compare policy limits, and understand the assistance process. Choose coverage based on the trip you are actually taking, not simply the lowest price. The best holiday memories should be the experiences you bring home, not the bills you never expected.
Need Help Choosing Coverage?
Guardian Insurance MX helps expats, retirees, digital nomads, families, and international travelers compare travel insurance options and understand the benefits that matter for their journeys. Our bilingual team can help explain emergency medical coverage, trip cancellation, baggage protection, assistance services, and the practical differences between plans.
Speak with an insurance advisor to compare options and receive personalized guidance before your next holiday trip.